Education Loans for Study Abroad: How to Secure Up to ₹50 Lakh Without Property Collateral
For middle-class Indian families, securing proof of funds for university tuition, visa blocked accounts, and living expenses is frequently the most stressful milestone of the study abroad journey. When families do not own unencumbered residential property, commercial real estate, or fixed deposits to pledge as collateral, securing an unsecured (non-collateral) education loan becomes the vital financial bridge.
Core Realities of Non-Collateral Financing
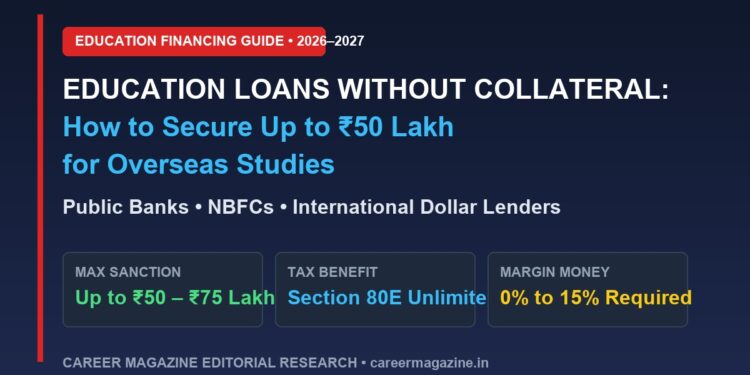
- Sanction Ceilings: Top NBFCs and private banks routinely sanction unsecured loans between ₹40 Lakh to ₹60 Lakh for top-ranked STEM, management, and tech programs.
- Co-Applicant Financial Health: Non-collateral domestic loans evaluate the co-signer’s (parent, sibling, spouse) verifiable ITR, monthly salary slips, and CIBIL credit score (aim for 700+).
- Dollar Loans Without Co-Signer: Specialized cross-border lenders evaluate the student’s future earning potential rather than ancestral Indian wealth or domestic co-signers.
- Tax Shield (Section 80E): The entire interest paid on education loans is 100% tax-deductible under Section 80E of the Indian Income Tax Act for up to 8 continuous assessment years, with no upper monetary cap.
The 3 Major Financing Channels for Indian Students
1. Public Sector Banks (SBI, Union Bank, Bank of Baroda)
Public sector banks offer the lowest interest rates in the market (typically 9.5% to 11.25%). While their collateral-backed loans (e.g., SBI Global Ed-Vantage) can go up to ₹1.5 Crore, their unsecured limits standardly cap at ₹7.5 Lakh under primary schemes, though special ties with premier tier-1 global institutes can occasionally push non-collateral sanctions higher.
2. Dedicated Private NBFCs (HDFC Credila, Avanse, InCred, Auxilo)
Non-Banking Financial Companies have revolutionized study abroad lending for Indian scholars. They feature fast digital approvals (within 3 to 7 business days) and provide up to ₹50–₹65 Lakh without collateral for accredited universities in the US, UK, Canada, and Germany. Interest rates range between 11.5% to 14.5% based on academic merit and co-applicant ITR.
3. International USD/EUR Lenders (Prodigy Finance, MPOWER Financing)
For students admitted to globally competitive master’s programs who lack high-income domestic co-signers, international fintech lenders provide loans disbursed directly in USD, EUR, or GBP:
- No Collateral & No Co-Signer Required: Underwriting is based purely on target program alumni placement data and graduation earning projections.
- No Currency Conversion Loss: Loans are disbursed directly in foreign currency to the overseas university.
- Repayment Flexibility: Repayment commences 6 months post-graduation, allowing students to service debt directly in foreign currency wages.
Lender Comparison Matrix
| Lender Category | Max Unsecured Limit | Interest Rate Range | Co-Signer Required? | Typical Processing Time |
|---|---|---|---|---|
| Public Sector Banks | ₹7.5 Lakh (Up to ₹40L for select top tier) | 9.5% – 11.2% | Yes (Strict income proof) | 3–5 Weeks |
| Private NBFCs | Up to ₹50 – ₹60 Lakh | 11.5% – 14.0% | Yes (Salary/ITR focused) | 4–7 Days |
| International Lenders | Up to 100% of Cost of Attendance | 11.9% – 14.9% (USD base) | No Co-Signer Needed | 5–10 Days |
Study Abroad & Scholarships Series Navigation
- Part 1: Study Abroad on a Budget: Top European Countries with Low Tuition
- Part 2: Top Full-Ride Scholarships for Indian Students: Chevening, DAAD & Erasmus Mundus
- Part 3: IELTS vs. TOEFL vs. Duolingo English Test: Comprehensive Score Benchmarks
- Part 4: STEM Courses Abroad: High-Paying Fields & Post-Study Work Visas
- Part 5: Education Loans Without Collateral: How to Secure Up to ₹50 Lakh (Current Article)
- Part 6: Winning Statement of Purpose (SOP) & Letter of Recommendation Framework